HONG KONG CAPITAL MARKETS
Hong Kong IPOs raised HK$210.2 billion in H1 2026: assessing price and the ability to exit
Hong Kong’s first-half IPO figures show a recovery in fundraising. They do not establish investment returns. We examine proceeds, cash conversion and a position-size test for exit risk.
Momentum returned; diligence remains transaction-specific
Hong Kong listings
IPO funds raised
Year-on-year increase in funds raised
What 87 listings establish—and what they do not
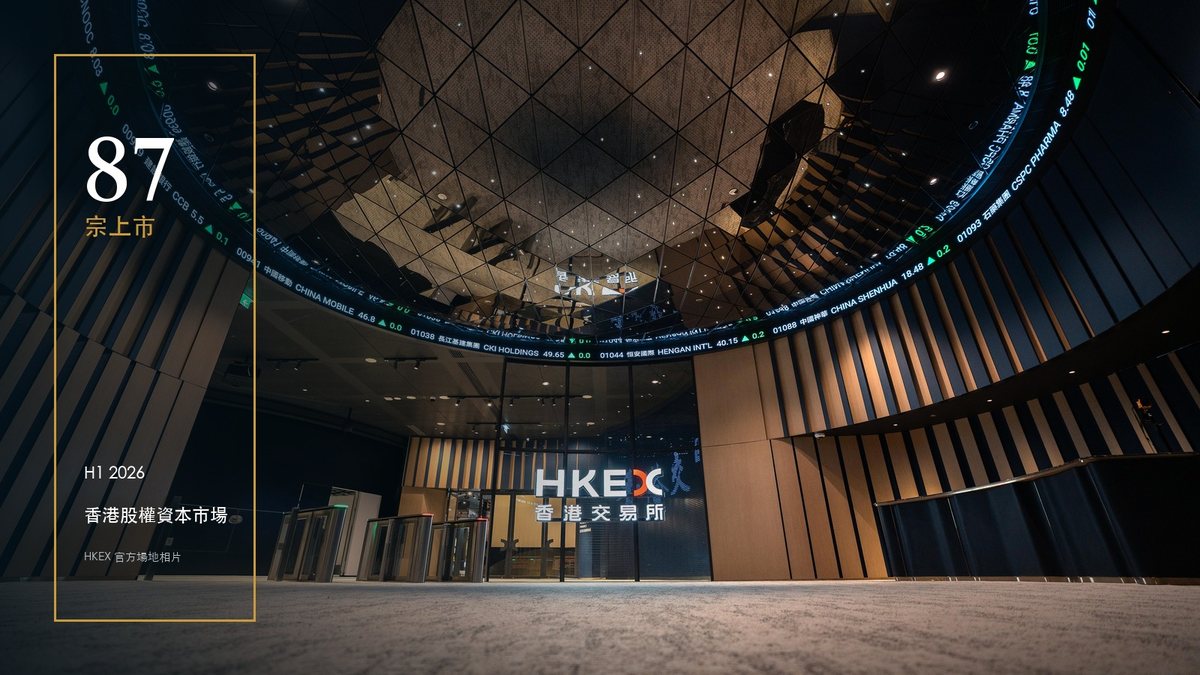
HKEX’s review, published on 16 July, records 87 listings raising HK$210.2 billion in the first half of 2026, against 44 listings and HK$109.4 billion a year earlier. Funds raised increased 92.1%. These are historical figures through 30 June, not market totals through October.
They answer whether companies were able to raise equity. They do not establish the value of a particular new listing or investors’ average return. Deal sizes, actual allocations, purchase and sale prices, and fees would all be needed to connect fundraising activity with an investor’s outcome.
 Open full-size image ↗
Follow the proceeds to the recipient
When reading a prospectus, distinguish newly issued shares from existing shares sold by shareholders, and identify who receives each part of the proceeds. The total offer size should not automatically be treated as new cash available to the company. Then compare the company’s net proceeds and intended uses with its existing balance sheet.
Repaying debt may reduce interest expense without adding production capacity or sales. An expansion plan needs a different assessment: when will spending occur, how much existing capacity is used, and what evidence supports demand? G70’s analytical test is whether the proposed use can be connected to future cash flows. This is a method, not an assessment of any particular issuer.
Align the earnings denominator before comparing prices
A price-to-earnings comparison needs consistent definitions. Are earnings historical or forecast? Do they include a one-off disposal gain? Does the share count reflect the IPO and potential dilution? If receivables rise alongside reported revenue, operating cash flow deserves a separate look: recognised revenue is not necessarily cash collected.
For a loss-making company, a price-to-earnings ratio cannot answer the question. A more useful exercise is to estimate how long existing cash and net IPO proceeds could cover operations and committed investment. Slower growth may bring the next financing need forward. Such estimates require explicit cash-burn and revenue assumptions; they are not realised results.
Test exit capacity against the proposed holding
HKEX’s FAQs describe cornerstone investors as having assured IPO allocations, with the relevant IPO shares subject to a six-month lock-up from listing. The prospectus remains necessary to establish the particular arrangements and exceptions. Expiry allows shares to become available for sale; it does not establish that holders will sell.
Consider a hypothetical HK$5 million holding. If reference daily turnover were HK$10 million and sales were limited by assumption to 5% of that amount each day, disposal would take about ten trading days. If turnover halved, it would take about twenty. This excludes falling prices, bid–ask spreads and market impact; it is not a turnover forecast.
Before an IPO, there is no actual post-listing trading history. Any such test must therefore use clearly labelled scenarios, then be revisited with observed data after listing. A family with taxes, loan payments or other cash commitments should not automatically count expected sale proceeds as cash available on a fixed date.
 Open full-size image ↗
Record a reason that evidence could overturn
A useful subscription record connects the company’s use of net proceeds, the earnings or cash-flow assumptions behind the valuation, and the time needed to exit under a low-turnover scenario. If one cannot be explained, postponing the decision remains an option.
G70 can coordinate the information with the family and relevant professional firms, including how cash requirements fit the family’s wider arrangements. Security research, suitability assessments and regulated investment services are provided independently by appropriately licensed institutions.
G70 IPO CHECK
Connect the subscription case to evidence
Explain what the company receives, what supports the price, and what an exit would require.
- Separate company net proceeds from shareholder sale proceeds
- Align earnings, cash flow and potential dilution
- Test the holding against a low-turnover scenario
Official and primary sources
- HKEX | Hong Kong Markets H1 2026 Update
- HKEX | Top questions: cornerstone investors (checked 21 October 2026)
Originally published 17 August 2026. This remains an analysis of historical H1 2026 data. Sources rechecked and content updated 21 October 2026; market figures are not current totals through the update date.